

This is the monthly review of The Mispriced Portfolio.
The goal is not to explain every market move but to keep the portfolio process visible, consistent, and accountable.
I run a concentrated portfolio built from the same research process I publish here.
I invest my own capital alongside the research, and I usually keep the portfolio focused — typically around 15 positions.
Research Goal
Building a concentrated portfolio of liquid opportunities that can compound capital at attractive rates over the long term.
I look for a small number of positions where quality, valuation, expected return, and downside line up better than average.
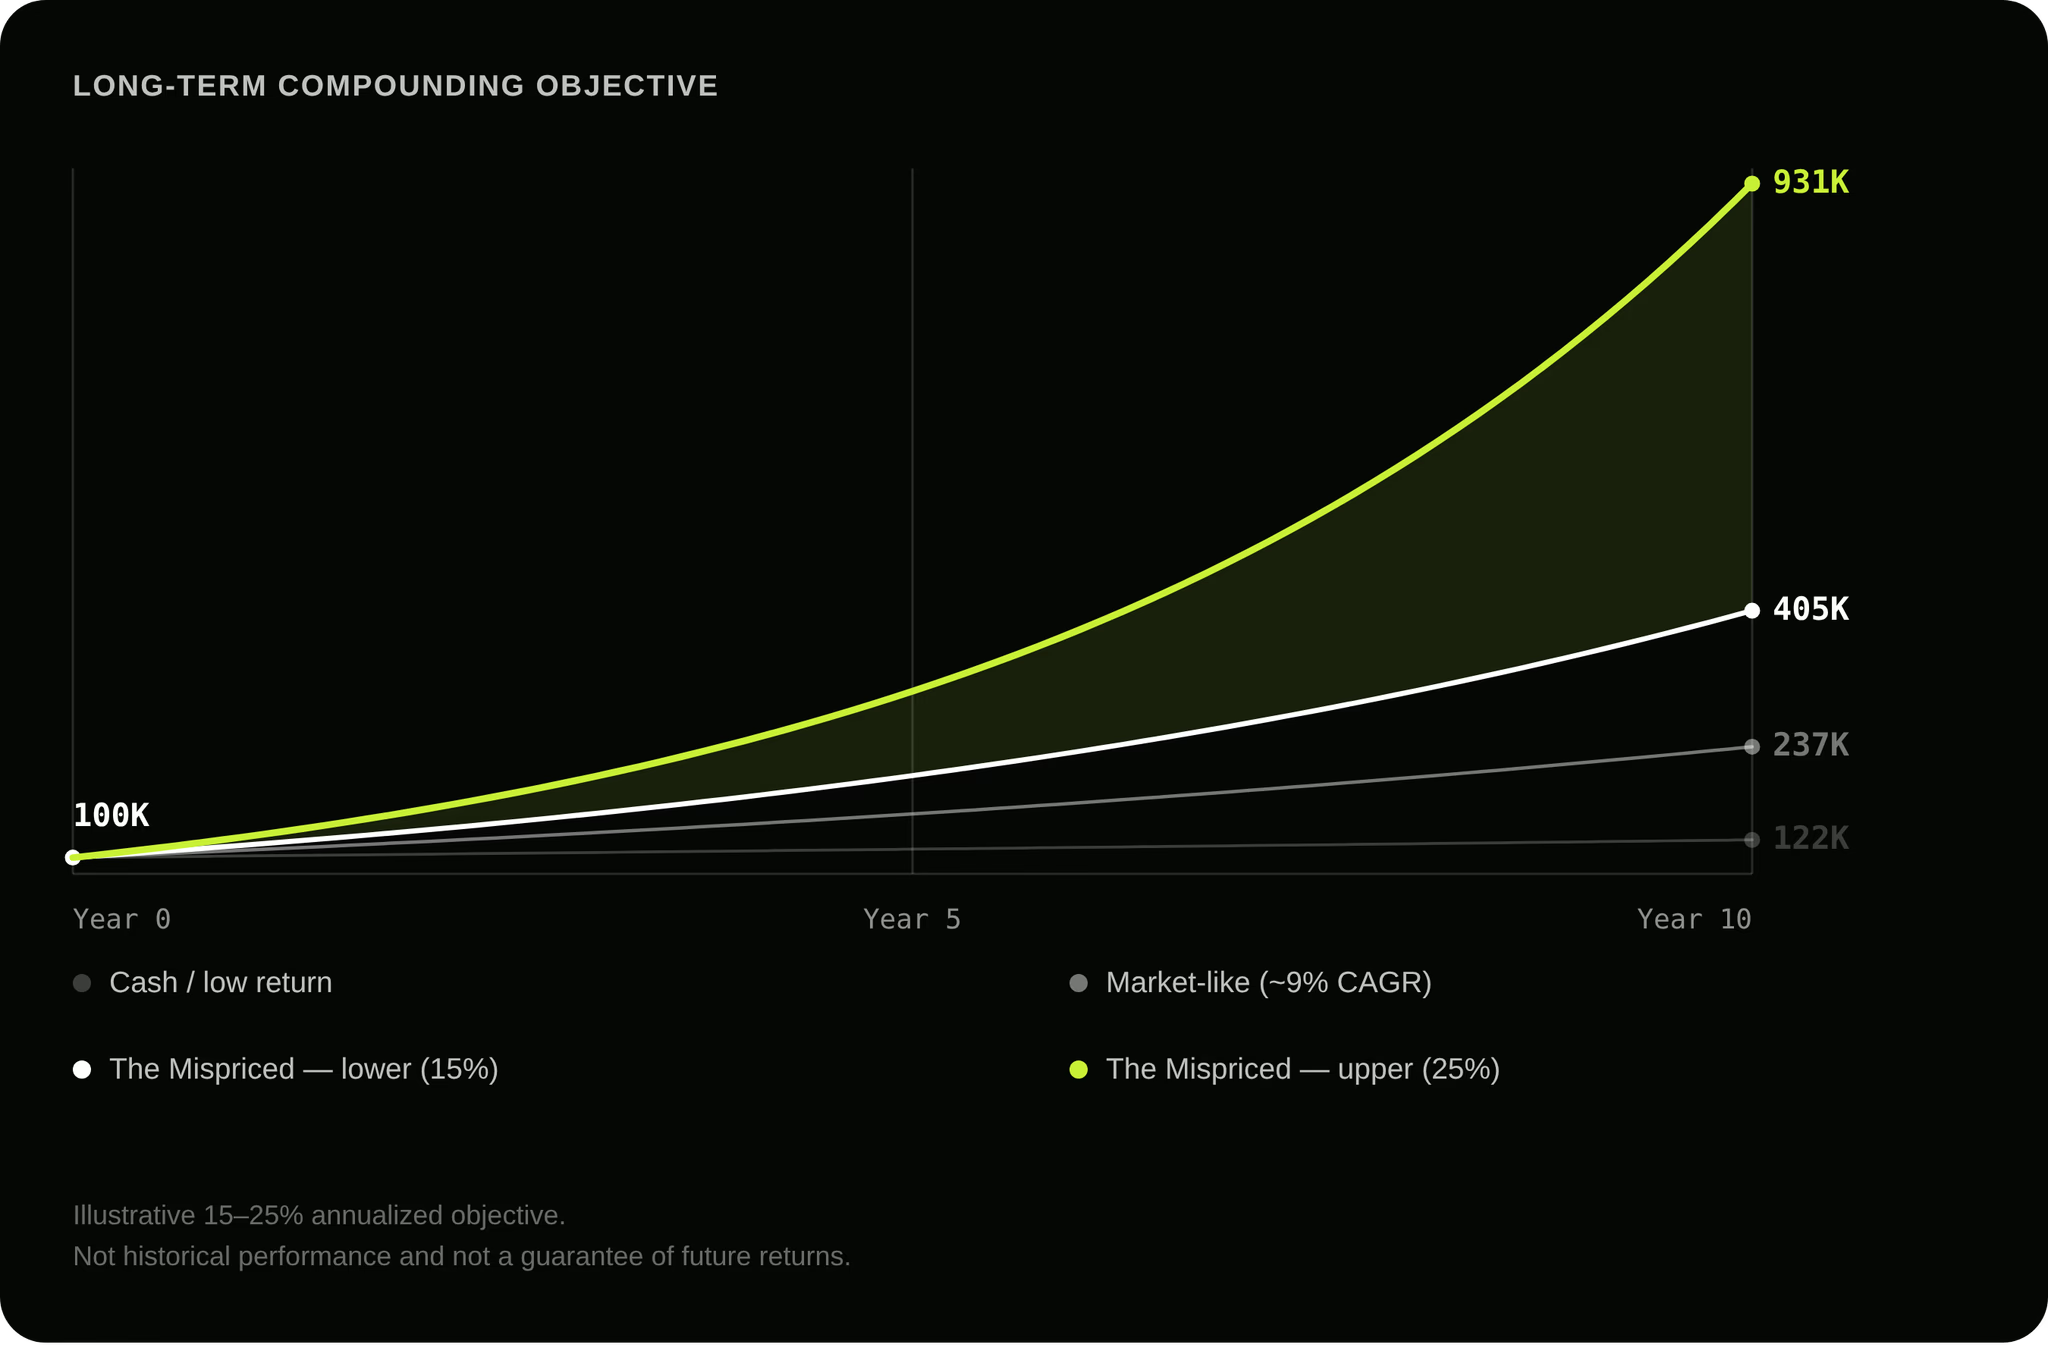
The long-term target to build a process that can aim for 15%+ annualized returns over time.
Portfolio Snapshot
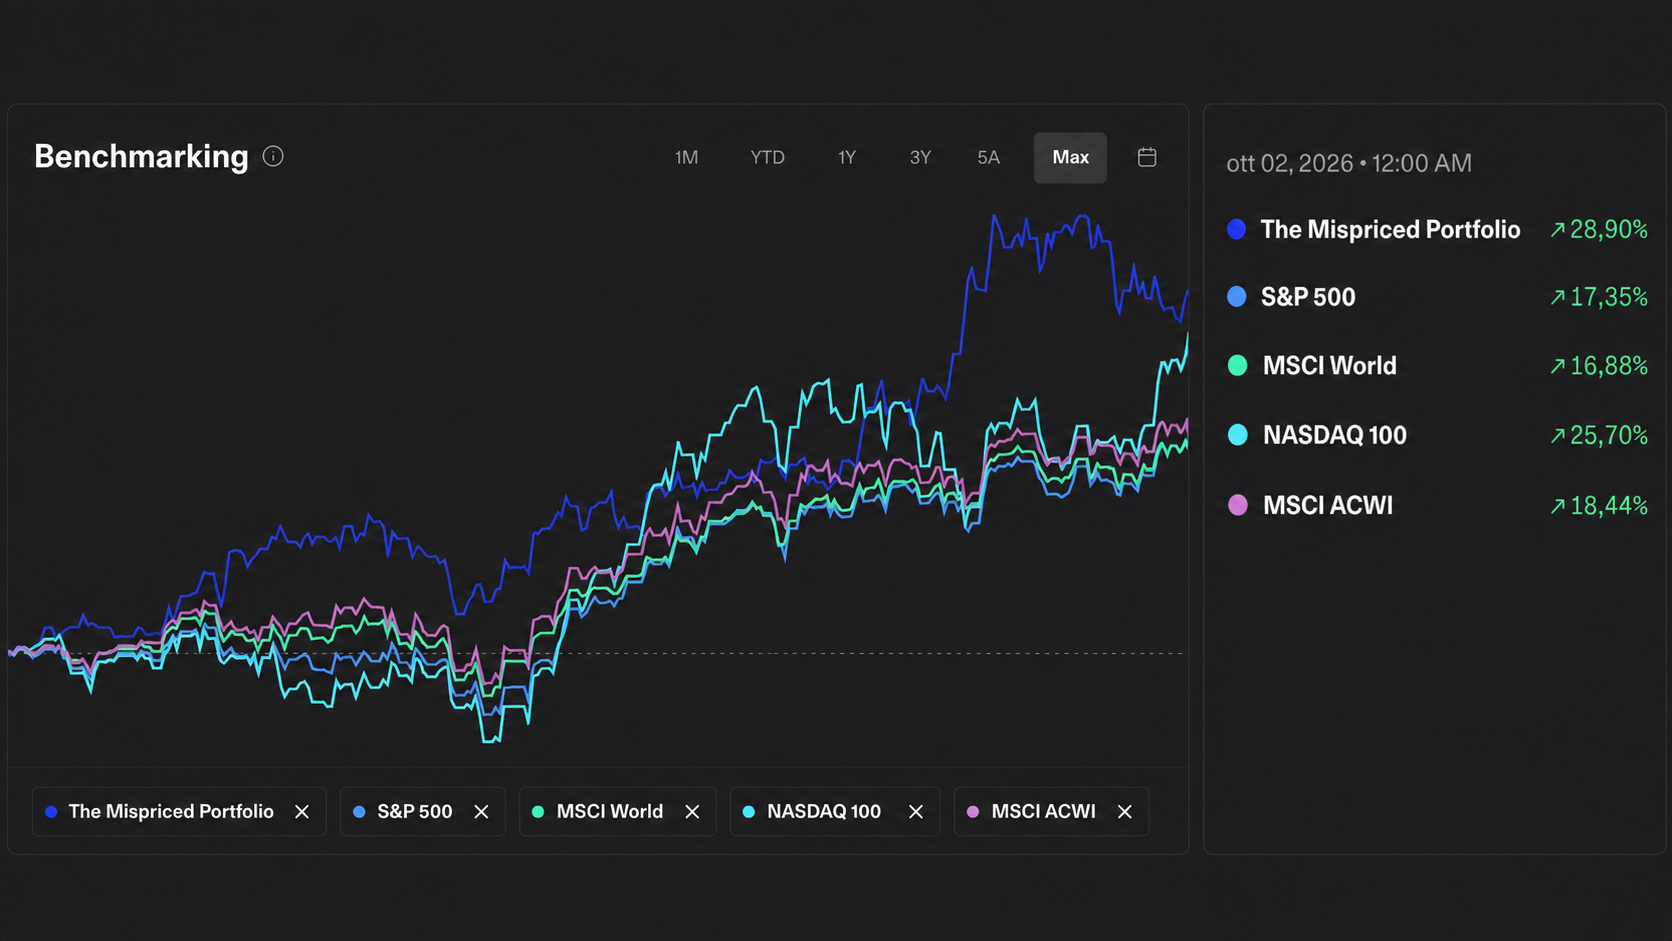
Since Nov 2025
True Time-Weighted Rate of Return: +28.9%
Return on Invested Capital: +4.3%
Realized Gains: +16.95%
Dividend Contribution: +0.66%
September Moves
Every investment is made with one goal: owning the opportunities with the highest QPOS scores. The portfolio is built with a permanent capital mindset, but individual positions are not permanent. A position may remain in the portfolio for years, but it may also be reduced or exited after only a few weeks if a better opportunity emerges. Holding is a decision. Selling is a decision. Reallocating capital is a decision. Every position has to keep earning its place in the portfolio.
BUY
Autotrader Group
Crocs
Nvidia
Eckert & Ziegler
ADD
Nextpower
Trade Desk
Hamilton Lane
ExlService
Wavestone
Autotrader Group
BTCs
Deckers Outdoor
Applovin
EXIT
Microsoft → +28.28%
Yelp → -13.08%
Cirrus Logic → +2.41%
NXP Semiconductors → +0.90%
NAPCO Security → +2.85%
Review
Over the past month, I made several portfolio rebalancing decisions. These moves naturally had an impact on short-term performance, particularly around ROIC, but I believe the capital is now better positioned and that these changes can create better outcomes over the coming months.
The portfolio remains aligned with the IPS. Measured using True Time-Weighted Rate of Return (TTWROR), the portfolio has returned 28.90%, compared with 17.35% for the S&P 500, 16.88% for MSCI World, 25.70% for the Nasdaq 100, and 18.44% for MSCI ACWI since inception.
The weakest contributors recently have been The Trade Desk, Deckers, and Wavestone. I am monitoring all three closely. For now, I do not see evidence that the original theses have been invalidated, although there has been some weakening—particularly in The Trade Desk. Weak price action alone is not a reason to sell. What matters is whether the underlying business, valuation, odds, or risk thesis has materially changed.
What I’m Watching
The broader thinking remains the one discussed in “Dispersion Is the Opportunity.” I am less interested in predicting whether the market as a whole goes up or down and more interested in understanding where expectations, fundamentals, and prices are moving apart.
A few things matter most right now: the cost of capital remains meaningfully higher than during the previous decade; index concentration means passive exposure increasingly embeds a large bet on a small number of companies; heavy AI capital spending raises an important question about future returns on incremental capital; and liquidity remains an important variable in a highly leveraged financial system. At the same time, wider dispersion should create more opportunities for selective capital allocation.
Current Portfolio
14 holdings
