

Some ideas deserve attention before they deserve capital.
This series is where we study one asset at a time, define the risk, and decide what price would make the bet worth taking.
This is not financial advice.
This week’s Research Note is about:
Regeneron Pharmaceuticals — REGN -1.88%↓
1. Why We Are Watching It
We are watching Regeneron Pharmaceuticals because:
It is a high-quality biotech with strong cash generation.
Dupixent is still growing fast and remains a major long-term driver.
The price has moved into a more interesting range.
The balance sheet is strong.
Management is returning capital through buybacks.
The simple thesis:
REGN is a high-quality biotech compounder, but the investment case depends on whether Dupixent, EYLEA HD, Libtayo, and the pipeline can more than offset the decline of legacy EYLEA.
The key question:
Can Regeneron replace the fading EYLEA profit pool without destroying returns on capital?
2. What It Does
Regeneron discovers, develops, manufactures, and sells medicines.
Its main areas are:
Eye disease
Immunology
Oncology
Rare diseases
It makes money through:
Direct U.S. product sales, especially EYLEA and EYLEA HD
Collaboration revenue and profit-share with Sanofi, mainly Dupixent
Collaboration revenue with Bayer for EYLEA outside the U.S.
New product growth from Libtayo and the broader pipeline
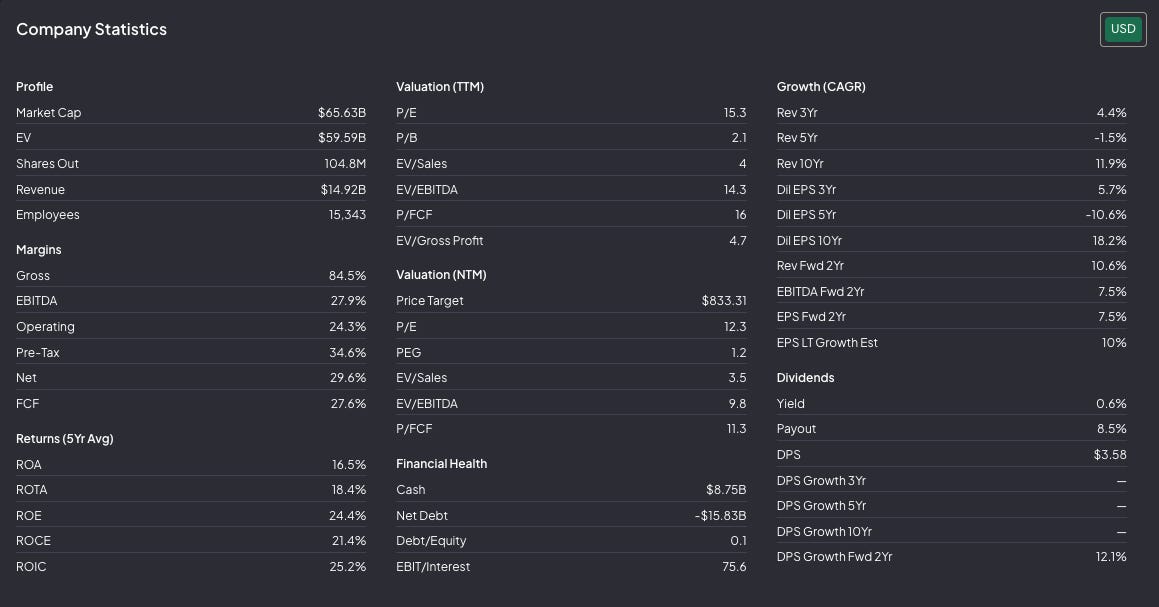
Dupixent and EYLEA remain the core economic engines. The company also has a deep clinical pipeline, with almost 50 candidates in development according to our last memo. Regeneron had strong economic quality, including 2025 free cash flow of $4.08 billion on $14.34 billion of revenue and a 5-year average ROIC of 23%.
3. What We Like
The attractive parts:
High economic quality: REGN has historically produced strong margins, strong free cash flow, and high returns on capital. That matters because biotech can be volatile, but a company with strong cash generation has more room to fund R&D, defend franchises, and buy back stock.
Dupixent remains powerful: Q1 2026 showed Dupixent growth of +33%. This reduces the risk that REGN becomes a single-product decline story.
EYLEA HD is helping: Legacy EYLEA remains under pressure, but EYLEA HD grew +52% in Q1 2026. It is not fully solving the problem yet, but it is improving the bridge.
Libtayo is becoming more relevant: Libtayo grew +54% in Q1 2026. It is still not as central as Dupixent or EYLEA, but it adds another growth driver.
Balance sheet and buybacks: REGN has a strong balance sheet and is becoming more aggressive with repurchases. The company bought back $803 million in Q1 and announced a new $3 billion buyback program.
What we’re really looking for:
A durable biotech with strong cash generation, disciplined capital allocation, and enough future growth to offset patent and product-cycle risk.
4. What Scares Us
The risks:
Legacy EYLEA decline: this is the main problem. U.S. legacy EYLEA was down 36%, and combined U.S. EYLEA HD + EYLEA was still down 10%. EYLEA HD is helping, but not enough yet.
Patent and competition risk: biotech moats are real, but they are not permanent. They depend on patents, clinical execution, data, regulation, and product cycles. EYLEA decline shows that even strong pharma franchises can weaken after exclusivity pressure.
Pipeline risk: the pipeline is large, but not every candidate becomes a product. A large pipeline improves the odds, but it does not remove uncertainty.
5. Quality Score
Business Quality — 4/5
Regeneron has strong intellectual property, deep scientific know-how, important medicines, and durable franchises. The weakness is that pharma durability depends on patents and product cycles.
Financial Quality — 5/5
The economics are strong: high margins, strong free cash flow, high ROIC, and a strong balance sheet. This is the best part of the case.
Management / Execution Quality — 3/5
Management has built a serious biotech platform and is returning capital through buybacks. The main thing to monitor is capital allocation discipline, especially if growth slows and the company feels pressure to buy external assets.
Total Score
12/15
6. Fair Value Range
Our rough fair value range:
