

Some ideas deserve attention before they deserve capital.
This series is where we study one asset at a time, define the risk, and decide what price would make the bet worth taking.
This week’s Research Note is about:
ExlService Holdings — EXLS 2.15%↑
1. Why We Are Watching It
We are watching ExlService Holdings because:
It combines data, analytics, AI, and operational services inside complex enterprise workflows.
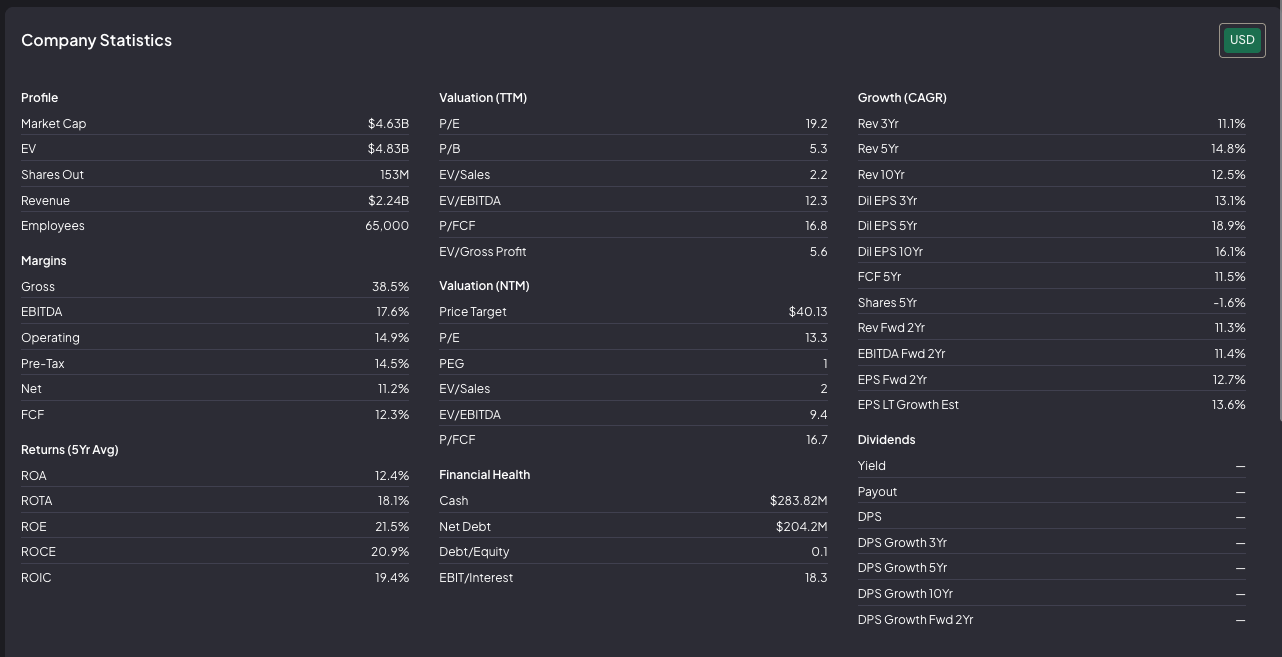
More than 75% of revenue is recurring, with net revenue retention above 111%.
The business has improved its ROIC, margins, and cash generation while maintaining a relatively light capital base.
Enterprise AI could create a long reinvestment runway, especially in regulated industries where data quality, context, and trust matter.
The simple thesis:
EXL could become a durable compounder by helping large companies move AI from experimentation into mission-critical production.
The key question:
Can EXL turn strong revenue growth into durable free cash flow per share without allowing stock-based compensation, acquisitions, or AI commoditization to weaken the economics?
2. What It Does
ExlService Holdings helps large companies use data and AI to make decisions, automate complex processes, and modernize important workflows.
Its main customers operate in areas such as insurance, healthcare, and banking.
EXL makes money through:
Data, analytics, and AI services
Ongoing management of complex business processes
Proprietary platforms, tools, and intellectual property
Expansion and cross-selling within existing customer relationships
More than three quarters of revenue is recurring.
3. What We Like
The attractive parts:
Mission-critical customer relationships: EXL is integrated into workflows that clients cannot change casually. Its industry knowledge and position inside regulated processes create meaningful switching costs.
Strong recurring economics: more than 75% of revenue is recurring. Net revenue retention is above 111%, suggesting that existing customers tend to expand their spending over time. The company’s average net promoter score over the past five years has also been above 80.
High returns on capital: reported ROIC increased from 8.9% in 2020 to 20.2% in 2025. That matters because growth creates the most value when a company can reinvest at attractive returns.
Strong cash conversion: EXL generated approximately $298 million of free cash flow in 2025, equal to 119% of net income. Capital expenditures were only $52.6 million, which supports the view that this is a relatively asset-light business.
A credible enterprise AI position: EXL works at the intersection of industry data, domain knowledge, operational execution, and AI. That combination may be more durable than selling generic AI services alone.
What we’re really looking for:
A durable business with attractive economics, clear risks, and a price that gives us room to be wrong.
4. What Scares Us
The risks:
AI could weaken the service model: AI is both the opportunity and the threat. More accessible models could automate labor-intensive work faster than EXL can replace it with higher-value platforms and intellectual property.
Stock-based compensation is rising: second-quarter stock-based compensation increased from $16.4 million to $24.6 million, or roughly 50%. Adjusted earnings exclude this cost, but shareholders still bear its economic effect.
Revenue growth is not fully reaching GAAP earnings: second-quarter revenue grew 15.6%, but GAAP EPS increased only from $0.40 to $0.42. GAAP operating margin declined from 15.8% to 14.7%. The top-line result was strong. The per-share economic result was less convincing.
The iMerit acquisition adds execution risk: the acquisition could cost up to $310 million, including upfront and future consideration. It may strengthen EXL’s AI capabilities, but the company still has to prove the integration, talent retention, and returns on invested capital.
The moat is meaningful, but not absolute: EXL has high switching costs, recurring revenue, and strong vertical expertise. It does not have a monopoly, a dominant network effect, or an irreplaceable technology platform. Large consultants, IT service providers, and AI specialists remain credible competitors.
5. Quality Score
Business Quality — 4.5/5
High recurring revenue
Strong customer retention
Meaningful switching costs
Mission-critical workflows
Attractive positions in regulated industries
Financial Quality — 4.5/5
ROIC above 20% in 2025
Strong historical free cash flow conversion
Low capital intensity
Moderate leverage
Good reinvestment potential
Management / Execution Quality — 4/5
Strong historical operating execution
Organic investment increased substantially
Capital allocation has supported higher ROIC
The balance sheet has remained flexible
Share count declined in the latest quarter
Total Score
13/15
6. Fair Value Range
Our rough fair value range:
