

This week’s Research Note is about:
Yelp — YELP 0.00%↑
1. Why We Are Watching It
We are watching Yelp because:
It is a highly cash-generative, asset-light business trading at a depressed valuation.
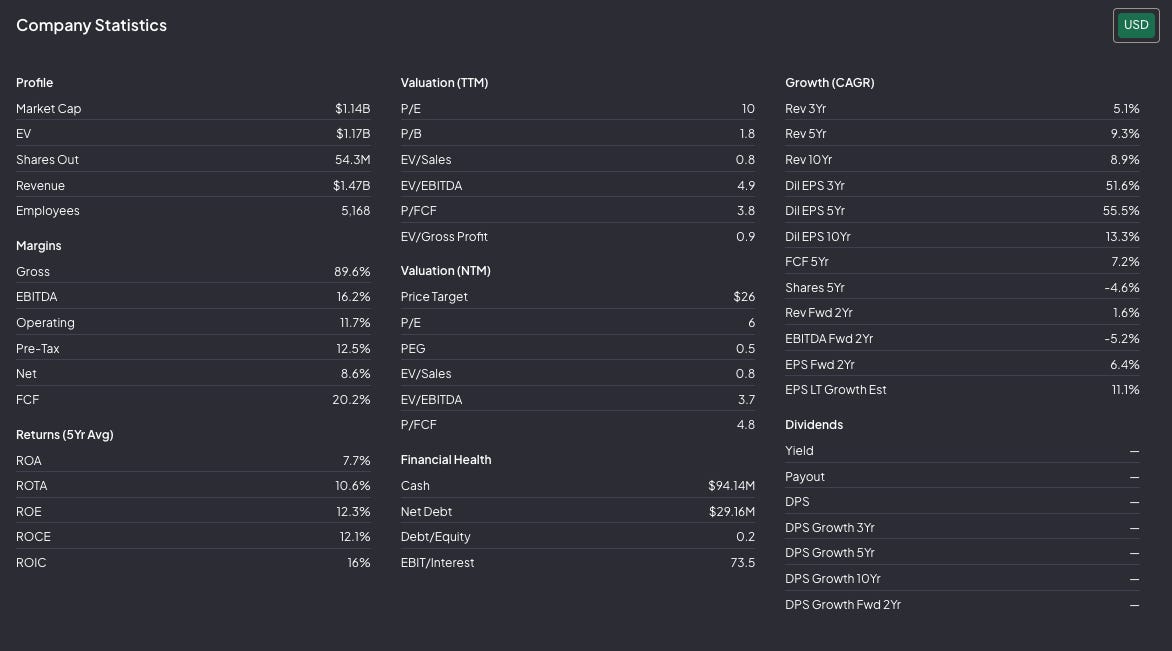
Its five-year average ROIC is around 16%, while free cash flow margins remain attractive.
The market appears to be pricing in stagnation or structural decline, creating potentially interesting asymmetry if the franchise proves more durable than expected.
The simple thesis:
Yelp may be worth considerably more than the market price if its current cash generation survives the transition in local search.
The key question:
Is Yelp building a second growth engine, or simply using new products to offset the slow erosion of its core business?
2. What It Does
Yelp is a local discovery platform that connects consumers with local businesses through reviews, search, leads, and transactions.
It makes money mainly through:
Performance-based advertising from local businesses
Services-related lead generation
Newer businesses including Hatch, Yelp Host, API and data licensing, and food-ordering products
Advertising still represents roughly 95% of revenue, so this remains primarily an advertising business today.
The newer products matter because Yelp needs another source of growth.
Hatch, AI tools, restaurant software, and data licensing could become that second leg.
But they have not proven it yet.
3. What We Like
The attractive parts:
Strong cash generation: Yelp generated about $324 million of free cash flow in 2025 on roughly $1.47 billion of revenue.
The business is highly asset-light, with gross margins around 90% and free cash flow margin around 20%.
A real, although imperfect, moat: Yelp still owns a large review corpus, valuable local-intent data, a recognized consumer brand, and a marketplace connecting consumers with businesses. More reviews improve discovery. Better discovery attracts users. User intent creates value for advertisers.
The network effect is real.
Aggressive share reduction: management has used significant free cash flow for repurchases. Yelp spent roughly $292 million on buybacks in 2025, reducing the share count including equity awards by roughly 10%.
At depressed prices, continued repurchases can materially increase owner earnings per share if the underlying cash flow remains durable.
Founder alignment: Founder and CEO Jeremy Stoppelman owned roughly 5.5% of the company. Compensation also includes performance measures tied to revenue, adjusted EBITDA, and shareholder returns.
4. What Scares Us
The risks:
Google and AI disintermediation: Yelp does not fully control its customer acquisition. Google remains an important source of web traffic, while Maps, AI-generated answers, and changing search behavior could reduce the need for users to visit Yelp directly.
The core advertising engine is barely growing: in Q2 2026, advertising revenue declined 3%. Services was roughly flat, Restaurants, Retail & Other declined 10%, and total ad clicks fell 5%. Better monetization can offset lower traffic for a while but it cannot do it forever.
Capital allocation is becoming more important: Yelp spent roughly $264 million on the Hatch acquisition during the first half of 2026 while also continuing large buybacks. Part of the transaction was financed through a revolving credit facility. The risk is not that Yelp cannot generate cash.
The risk is that management uses that cash to buy growth at lower returns than the original business produced.
5. Quality Score
Business Quality — 3/5
Real brand
Proprietary review content
Local-intent data
Network effects
Financial Quality — 4/5
Capital-light business
High ROIC
Healthy balance sheet
Management Quality — 2.5/5
Founder ownership
Share repurchases
Reducing stock-based compensation
Total Score
9.5/15
6. Fair Value Range
Our rough fair value range:
