

The economy is increasingly K-shaped.
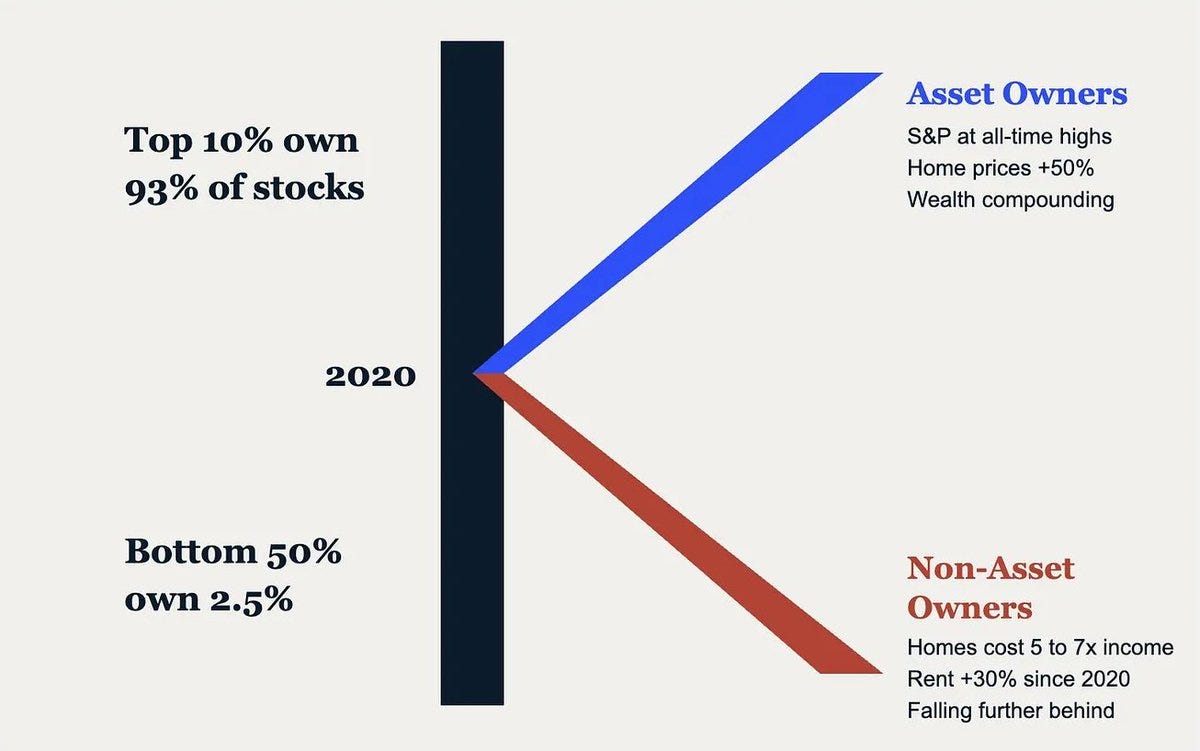
While lower- and middle-income households struggle with inflation, declining purchasing power, and rising debt, wealthier households continue to benefit from rising asset prices, particularly stocks and real estate.
Two different economic realities are emerging.
And this divergence creates interesting opportunities for investors.
One area that stands out is ultra-luxury.
Unlike mass-market consumers, ultra-high-net-worth individuals are less dependent on wages or credit to finance their spending. Their purchasing decisions are driven more by accumulated wealth than by disposable income.
This makes businesses serving the very wealthy potentially more resilient to the pressures affecting the broader economy.
And few products represent this dynamic better than luxury yachts.
One company on The Mispriced universe is Sanlorenzo ($SL).
Sanlorenzo is an Italian luxury yacht and superyacht manufacturer serving some of the wealthiest individuals in the world.
Its competitive advantage comes from its brand, customization, exclusivity, and deliberately limited production volumes.
In a K-shaped economy, Sanlorenzo operates on the stronger side of the divide.
Of course, wealthy customers are not immune to economic downturns. But their financial flexibility, combined with Sanlorenzo’s positioning in the high-end market, makes the business particularly interesting to study.
The question is whether that quality is already reflected in the stock price.
Let’s dive in:
SanLorenzo — $SL
0. Topics Covered
Why We Are Watching It
What It Does
What We Like
What Scares Us
Quality Score
Fair Value Range
Scenario Range
Buy Zone
Margin of Safety
Expected Value
QPOS Score + View
Final Takeaway
Let’s go.
1. Why We Are Watching It
We are watching Sanlorenzo for three reasons.
A valuable luxury brand → Sanlorenzo operates in an exclusive segment where craftsmanship, customization, scarcity, and customer relationships support pricing power.
Attractive underlying economics → the business has demonstrated strong historical returns on invested capital, a conservative balance sheet, and a sizable order backlog.
A possible gap between quality and market expectations → the valuation still reflects meaningful cyclicality rather than assuming Sanlorenzo deserves the premium of a fully proven luxury compounder.
Can Sanlorenzo compound cash flow through a full economic cycle, or is the market right to value it as a cyclical luxury manufacturer?
2. What It Does
Sanlorenzo is an Italian luxury yacht manufacturer specializing in highly customized yachts and superyachts.
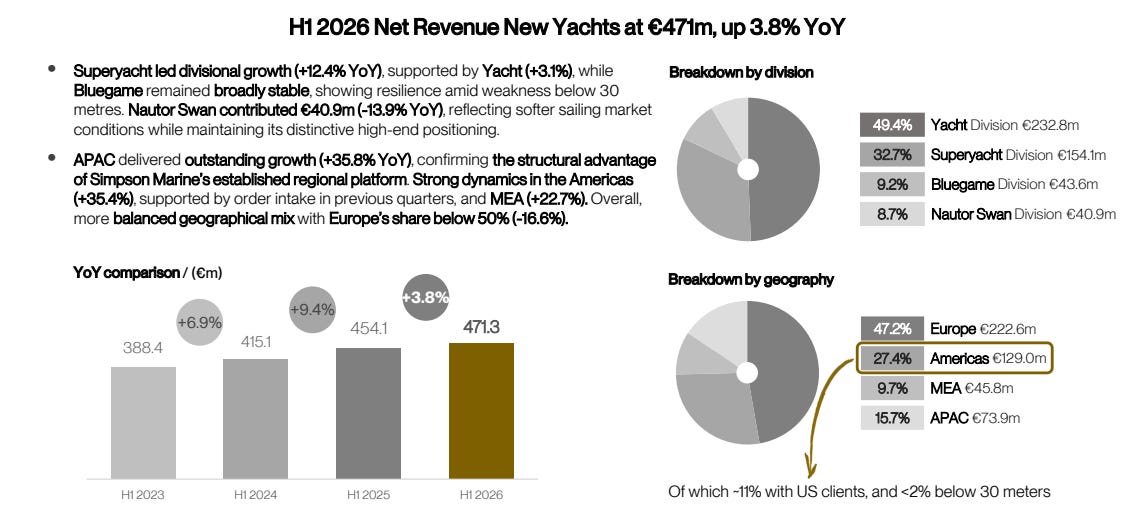
It operates through four divisions:
Yacht → luxury motor yachts
Superyacht → larger, more complex vessels for ultra-wealthy buyers
Bluegame → distinctive premium motor yachts
Nautor Swan → high-end sailing yachts and related luxury marine offerings.
Revenue comes primarily from new vessel sales, supported by additional services including maintenance, refitting, charter, and customer-related activities.
Customers pay for more than transportation.
They pay for design, personalization, craftsmanship, exclusivity, and reputation.
This matters because the business competes less on volume and more on the value of each customer relationship.
But there is a limit.
Yachts remain discretionary purchases, even for very wealthy customers.
The brand can be durable while demand remains cyclical.
3. What We Like
The attractive parts:
A real competitive advantage: Sanlorenzo has built a recognizable position in the highest end of the yacht market. Its limited production, customization, and relationships with wealthy customers create meaningful differentiation.
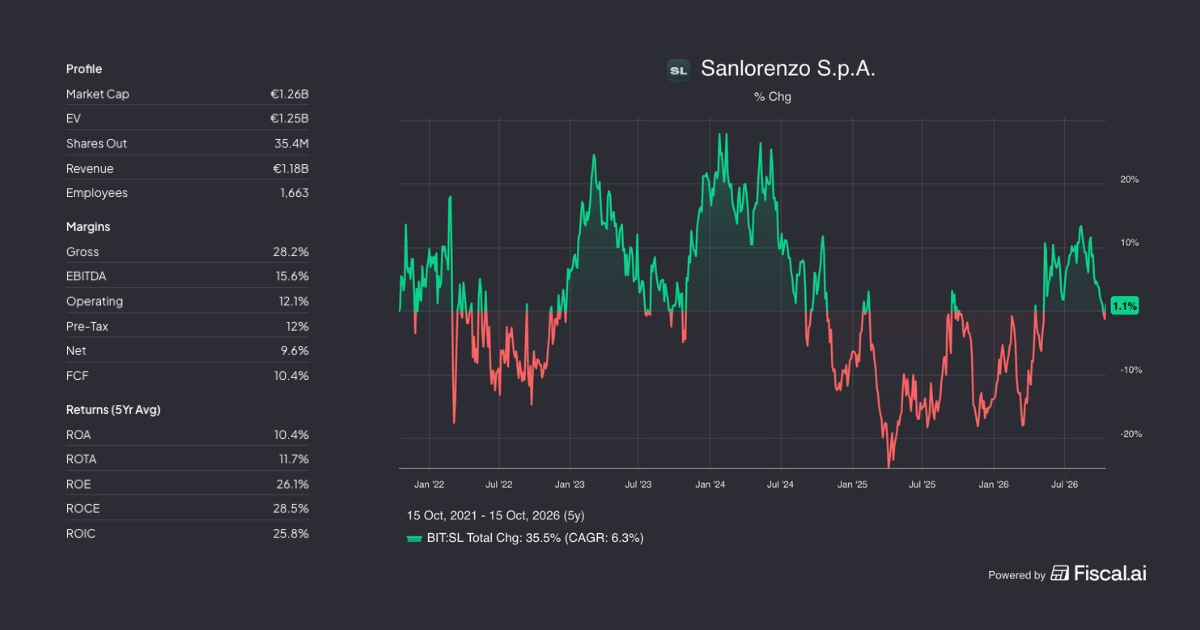
Attractive returns on capital: the company has historically generated attractive returns on the capital employed. The question is whether incremental investments and acquisitions will produce comparable returns.
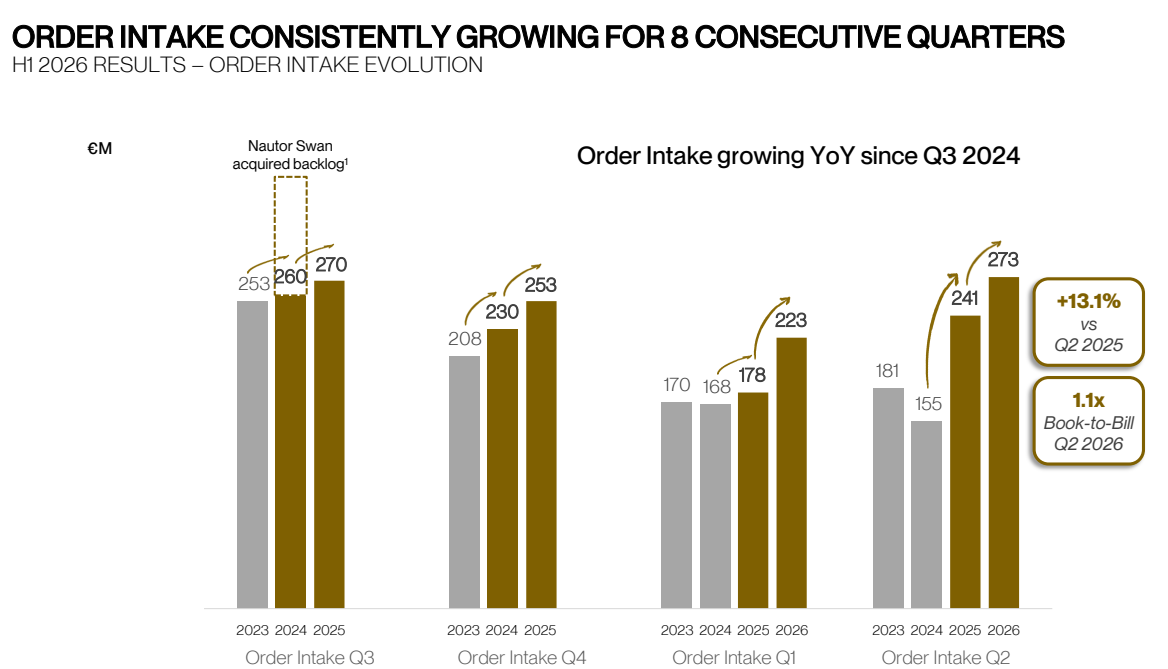
Strong order visibility: the H1 2026 update reported €496M of order intake, (up 18.3%), €1.03B of net backlog, book-to-bill of approximately 1.05x, and 83% coverage of 2026 revenue guidance.
Conservative balance sheet: Sanlorenzo reported €49.4M in net cash at H1 2026, following approximately €37M of dividend distributions and €80.2M of free cash flow.
4. What Scares Us
The risks:
Cyclical demand: Sanlorenzo serves ultra-high-net-worth customers, but their spending still depends on confidence, wealth, financial markets, and economic conditions.
Weak historical cash conversion: in 2025, FCF was approximately 48% of reported net income. Growth investments and working-capital requirements absorbed substantial cash. A company can report attractive earnings without generating equally attractive cash returns for shareholders.
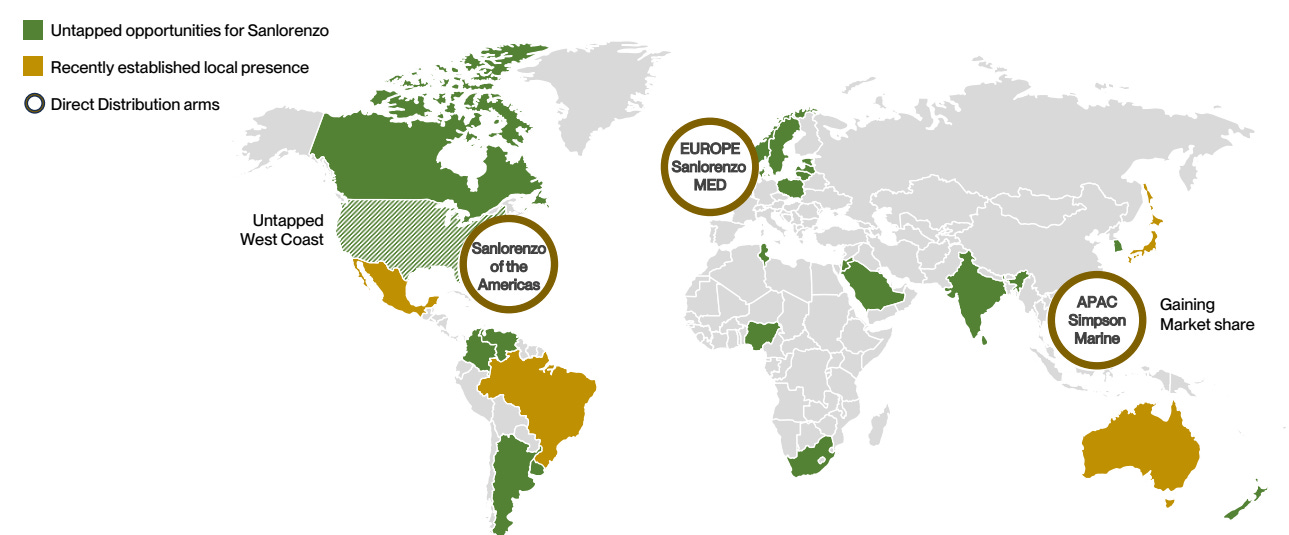
Execution and acquisition risk: the integration of Nautor Swan, expansion of direct distribution, and development of new vessels require capital and management attention. The potential minority investment related to The Italian Sea Group introduces another capital-allocation question.
Valuation and multiple compression: Sanlorenzo is not a pure recurring-revenue luxury business. A prolonged slowdown could reduce both earnings and the valuation multiple investors are willing to pay. That combination creates meaningful downside risk.
5. Quality Score
Business Quality — 4/5
Sanlorenzo benefits from a differentiated brand, scarcity, pricing power, and established customer relationships.
Financial Quality — 3/5
Historical ROIC is attractive, and the balance sheet is healthy. However, cash conversion remains uneven, and continued expansion requires meaningful capital.
Management Quality — 3/5
Capital allocation has generally been disciplined, with measured shareholder distributions and investment in growth.
But the long-term economics of acquisitions, particularly Nautor Swan, still need to be demonstrated.
Total Score
10/15
6. Fair Value Range
Our fair value range:
